
Dangerous Goods Declarations: Match the Paperwork to the Cargo
A dangerous goods declaration should accurately describe the consignment under the applicable transport rules and agree with the cargo, packaging and booking information.
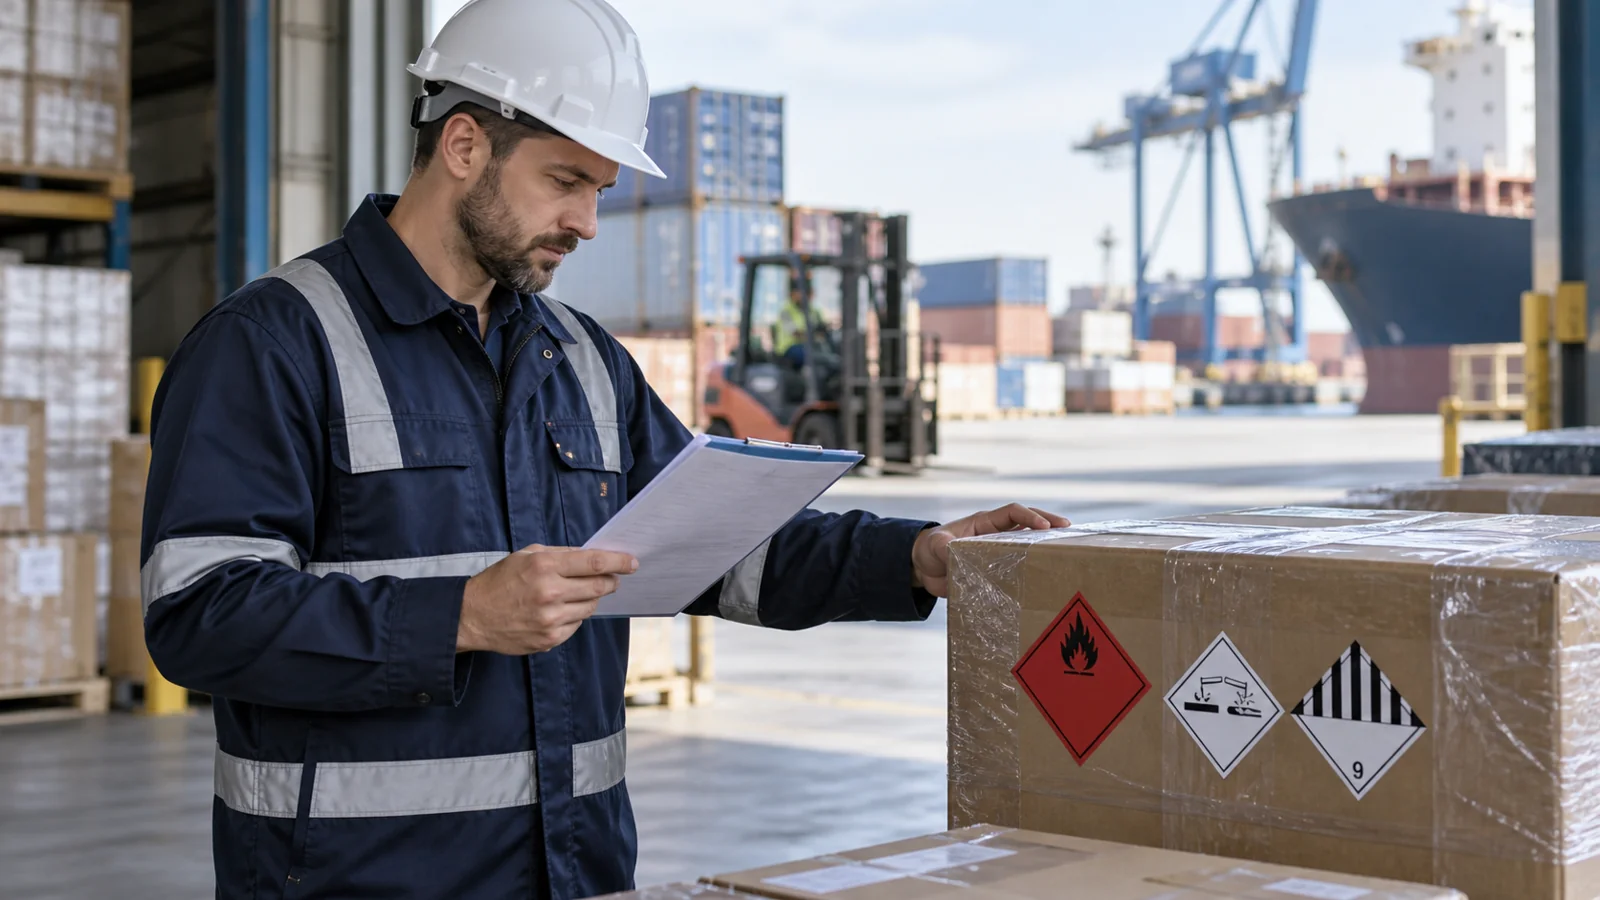
AI-generated editorial illustration.
What should a dangerous goods declaration match?
A dangerous goods declaration should accurately describe the consignment under the applicable transport rules and agree with the cargo, packaging and booking information. It is not simply a document to copy from an earlier shipment. Have competent personnel verify classification and required particulars, then reconcile the accepted booking with what is actually presented for carriage.
Use the sea-transport requirements
The IMO IMDG Code information identifies the maritime dangerous-goods framework. Amendment 42-24 became mandatory on 1 January 2026. This article is a records checklist, not a replacement for the Code, required training or a shipment-specific classification decision.
A product name alone may hide important differences in composition, concentration, condition or packaging. An old safety data sheet can also be inconsistent with the current product. Resolve discrepancies with the manufacturer and qualified dangerous-goods personnel before tendering the cargo; do not guess a classification to meet a vessel cutoff.
| Record | Reconciliation question | Responsible follow-up |
|---|---|---|
| Product information | Is this the current formulation? | Manufacturer or supplier |
| Classification | Does it apply to this consignment? | Competent DG personnel |
| Package details | Do type and quantity match loading? | Packing operation |
| Booking acceptance | Has the carrier accepted these particulars? | Booking team |
| Container identity | Is the declaration tied to the loaded unit? | Dispatch team |
Control revisions at the loading stage
In a fictional shipment, a supplier replaces a damaged package shortly before collection. The replacement has a different quantity, but the declaration and booking remain unchanged. The problem is not solved by retaining the earlier acceptance email: the accepted facts and presented cargo now differ.
Use a revision log that identifies who changed the information, when it changed and which parties received the update. Keep the final approved version clearly distinguishable from drafts. Where acceptance must be reconfirmed, allow time for that process rather than sending contradictory documents with the driver.
What does the insurer need?
Describe the actual goods, packaging, route and handling arrangements in the insurance submission. Carrier acceptance is not an insurance endorsement, and an insurance quote does not establish compliance with carriage rules. Material inaccuracies can complicate both operational response and assessment of cover.
If an incident occurs, preserve declarations, booking communications, packing records and photographs. Emergency and regulatory reporting should follow the applicable procedures; commercial claims notifications are a separate task. Avoid approaching damaged dangerous goods or opening packages simply to gather evidence.
For the wider shipment context, see the related cargo guide and marine cargo insurance. You can submit the proposed transit for review with the verified product information.
Key takeaways
- Reconcile the declaration with the actual goods and accepted booking.
- Use competent personnel and the applicable maritime requirements.
- Track late changes and keep safety reporting separate from insurance notification.
Frequently asked questions
What should a dangerous goods declaration match?
A dangerous goods declaration should accurately describe the consignment under the applicable transport rules and agree with the cargo, packaging and booking information. It is not simply a document to copy from an earlier shipment. Have competent personnel verify classification and required particulars, then reconcile the accepted booking with what is actually presented for carriage.
Sources & further reading
General information, not a coverage determination or offer. Actual cover is subject to policy wording, insurer terms, underwriting and applicable law.