
Pharmaceutical Shipping Insurance: Product Release and Cargo Damage
A temperature excursion is evidence requiring investigation, not automatic proof that the product is unusable or that insurance responds.
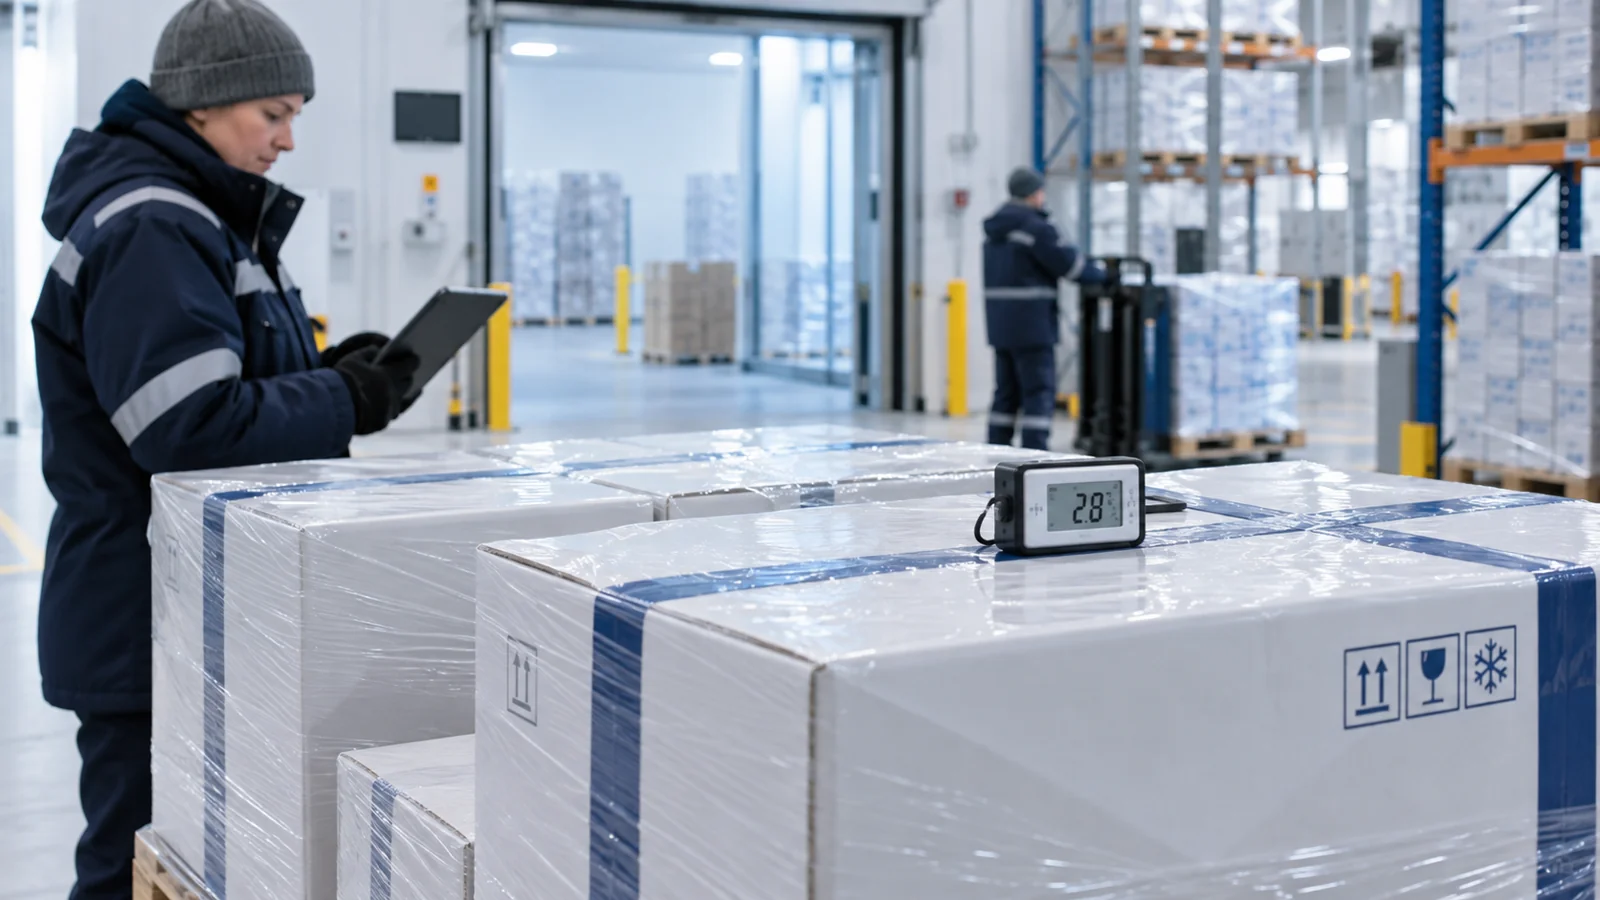
AI-generated editorial illustration.
Does a temperature excursion prove a pharmaceutical cargo claim?
A temperature excursion is evidence requiring investigation, not automatic proof that the product is unusable or that insurance responds. Product quality specialists must assess the shipment against its approved stability and handling requirements. The insurer separately examines the insured interest, actual loss, cause and policy terms. Keep those decisions connected through evidence without treating either as a substitute for the other.
Use product-specific acceptance criteria
The WHO model guidance for time- and temperature-sensitive pharmaceutical products provides an established technical baseline, published in 2011. It is not a new September 2026 rule or a universal temperature specification. The product's authorised requirements and applicable quality system remain central.
Before shipment, identify the responsible quality decision-maker, required monitoring, qualified transport arrangement and escalation contacts. A logistics team should know where to send an alarm and which records to preserve, without independently deciding that a medicine is safe to release.
| Evidence | Quality question | Insurance question |
|---|---|---|
| Product and batch | Which approved criteria apply? | Which insured goods are affected? |
| Logger record | What exposure occurred? | When and where did the event occur? |
| Calibration information | Is the measurement reliable? | How persuasive is the evidence? |
| Custody history | Which handling stage needs review? | Which transit or storage terms apply? |
| Disposition decision | Can the product be released? | What actual financial loss is claimed? |
Avoid destroying the investigation trail
Consider a fictional refrigerated shipment held during a port disruption. One logger records an excursion, but the receiver immediately deletes the download after copying a screenshot. The screenshot may omit timestamps, device identity or the complete trace. Retaining the original data, equipment records and quality assessment creates a stronger factual file.
Quarantine and product disposition should follow the quality system and applicable requirements. Coordinate any inspection or destruction evidence with the insurer where practicable, while meeting overriding product-safety duties. Insurance discussions should never be used to justify releasing unsuitable goods.
Explain the complete cold-chain arrangement
The submission should describe packaging or refrigeration, expected journey, transshipment, storage and contingency arrangements. Ask how the policy addresses temperature variation, delay, deterioration and any relevant conditions; a generic reference to refrigerated cargo is insufficient to answer every scenario.
Keep replacement costs, testing charges, disposal expenses and lost sales distinguishable. Their treatment may differ. The fact that a batch cannot be commercially released does not alone settle the insured cause or the amount recoverable under a cargo contract.
For more context, read the reefer insurance guide, review marine cargo insurance, or submit the cold-chain details.
Key takeaways
- Let qualified personnel assess product release using product-specific criteria.
- Preserve original monitoring data and the full custody history.
- Separate quality disposition, physical loss and policy response in the claim file.
Frequently asked questions
Does a temperature excursion prove a pharmaceutical cargo claim?
A temperature excursion is evidence requiring investigation, not automatic proof that the product is unusable or that insurance responds. Product quality specialists must assess the shipment against its approved stability and handling requirements. The insurer separately examines the insured interest, actual loss, cause and policy terms. Keep those decisions connected through evidence without treating either as a substitute for the other.
Sources & further reading
General information, not a coverage determination or offer. Actual cover is subject to policy wording, insurer terms, underwriting and applicable law.