
Fleet Marine Insurance: When One Programme Covers Multiple Ships
How to structure a multi-vessel programme with accurate schedules, clear insured interests, understood deductibles and controlled fleet changes.
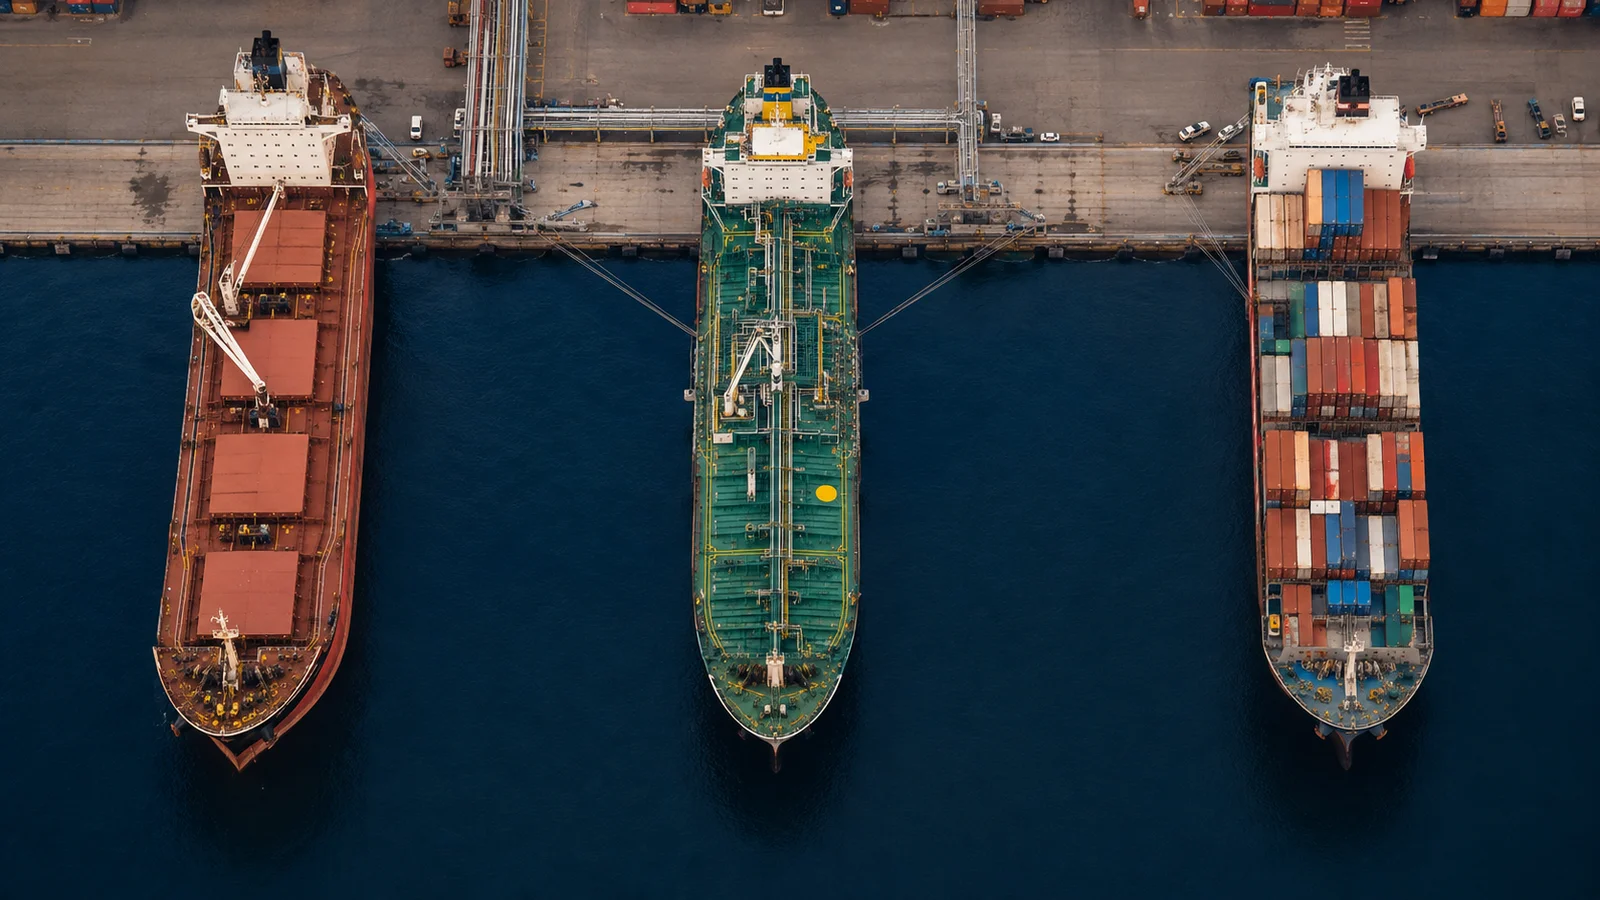
AI-generated editorial illustration.
> Editorial draft — pending specialist insurance and, where relevant, legal/compliance review. Updated 7 September 2026. Examples are hypothetical; the issued policy and applicable law determine actual cover.
Fleet marine insurance brings several vessels into a coordinated programme. It can simplify administration and support a consistent approach to terms, claims and renewal, but it does not mean every vessel automatically has identical cover. Each ship’s value, operation and insured parties still need to be identified.
The programme should make fleet management easier without hiding differences that matter to underwriting. The central document is a reliable vessel schedule supported by clear rules for additions, disposals and changes in trading.
Decide what belongs in the programme
Map the fleet by ownership, management, vessel type and operation. A group may own some ships, manage others and charter additional tonnage. These roles create different insured interests. The programme should say which entity and capacity is covered for each vessel.
Consider whether hull, liability, war and income covers should be coordinated under related arrangements or remain separate placements. Shared renewal dates can help administration, but alignment should serve the business’s needs rather than become an end in itself.
A diverse fleet may require vessel-specific deductibles, conditions or insurers. That is not necessarily a flaw. The important point is that the differences are intentional, documented and visible to the people operating the ships.
Build a dependable schedule
Include the IMO number where applicable, current name, flag, type, year built, class, registered owner, managers, insured value and currency. Add relevant limits, deductibles, trading and policy periods. Use stable identifiers so a name change does not create a duplicate vessel.
Reconcile the schedule with finance, technical and commercial records. A disposed ship should not remain accidentally insured, and a newly delivered ship should not depend on an informal email for its inclusion. Date the schedule and retain the accepted version.
For income cover, record each ship’s agreed daily amount and period. For liability, identify relevant entries or certificates. One fleet spreadsheet can index the programme while still linking to the authoritative policy documents.
Understand pricing and claims aggregation
An insurer may consider the fleet’s overall loss history and management alongside individual ships. A strong common management system can be useful evidence, but it does not erase a vessel’s specific defects or unusual operation.
Present claims with the exposure context: fleet size, policy periods, vessel type and changes in management. Separate large exceptional events from repeated moderate losses. Explain how corrective actions were applied across sister ships where appropriate.
Check whether any aggregate deductible, annual limit, bonus or adjustment mechanism applies. An aggregate can affect the entire fleet after several losses. Finance should understand how one vessel’s claim changes the remaining protection or retained cost for others.
Control additions and disposals
Some programmes provide agreed procedures for adding vessels, often with limits and reporting requirements. Others require individual prior acceptance. Read the clause and define who is authorised to request a change. Do not interpret an automatic-inclusion label as unlimited cover for any vessel the group acquires.
For a new ship, provide the technical and ownership information required and confirm the attachment time. For a sale, align deletion with the transfer of risk and any continuing insured interest. Keep lenders’ and charterers’ document requirements in the handover plan.
Changes of manager, flag, class or trading can also require notice. The operations system should trigger the insurance review rather than relying on one person remembering to forward an email.
Review common conditions and exceptions
Create a concise conditions register showing which rules apply fleet-wide and which apply to one ship. Include navigation limits, class requirements, survey obligations, deductibles and casualty-reporting instructions. Keep the wording authoritative and use the register as an operational aid.
Published insurer forms and rules show the importance of product-specific information and contractual detail. They are useful comparison references, not a universal fleet standard. See Gard marine insurance application forms and Gard rules, statutes and guidance.
For contracts within its scope, the UK Insurance Act’s fair-presentation framework is relevant to non-consumer disclosure. The governing law and contract terms should be checked for the actual fleet placement. See UK Insurance Act 2015. A centralised programme does not remove the need to disclose material vessel-specific facts.
A hypothetical mixed-fleet acquisition
A company insures six bulk carriers and acquires two product tankers. The commercial team assumes the fleet policy automatically includes them. The insurance team checks the addition clause and finds that the accepted operation and vessel categories need review.
It submits tanker-specific information, values, management plans and liability requirements. The insurer then decides whether to extend the programme and on what terms. The new ships are entered into the schedule only with an accurate record of acceptance and effective time.
The hypothetical illustrates why fleet growth should be an underwriting event as well as an accounting event. A common owner does not make new cargo systems or trading patterns identical to the existing risk.
Make renewal a coordinated decision
Bring technical, operations, finance and claims information together before renewal. Identify disposals, acquisitions, dry-docks and changed contracts expected during the next period. Use the same data set when comparing offers.
Assess premium alongside retained losses, administration, claims support and the clarity of vessel-specific terms. A programme is successful when every ship can be traced to accepted cover and the fleet team can manage changes without uncertainty.
Frequently asked questions
Does one fleet policy mean every ship has the same deductible?
No. Deductibles and conditions may vary by vessel or risk. The schedule and endorsements should make those differences explicit.
Are newly purchased vessels automatically covered?
Only if an agreed clause applies and its conditions are satisfied. Otherwise prior acceptance and binding confirmation are required.
Can chartered vessels join an owned fleet programme?
Possibly, but the charterer’s interest and liability differ from ownership. The insurer must accept the role, vessel and relevant terms.
Related reading and next step
What Affects Hull & Machinery Insurance Premiums?; Marine Insurance for Older Commercial Vessels; Voyage Marine Insurance vs Annual Marine Insurance.
Prepare a marine insurance enquiry with the relevant vessel, cargo and voyage details. Availability requires underwriting, compliance review and confirmed capacity. An enquiry, estimate or payment does not by itself establish cover.
Sources and editorial review
Prepared by the MarineEnergyCover editorial desk. No individual expert reviewer has yet approved this draft. Source references describe their own legal regimes or policy forms and do not establish MarineEnergyCover’s regulatory status, authority or available terms.
Frequently asked questions
Does one fleet policy mean every ship has the same deductible?
No. Deductibles and conditions may vary by vessel or risk. The schedule and endorsements should make those differences explicit.
Are newly purchased vessels automatically covered?
Only if an agreed clause applies and its conditions are satisfied. Otherwise prior acceptance and binding confirmation are required.
Can chartered vessels join an owned fleet programme?
Possibly, but the charterer’s interest and liability differ from ownership. The insurer must accept the role, vessel and relevant terms.
Sources & further reading
General information, not a coverage determination or offer. Actual cover is subject to policy wording, insurer terms, underwriting and applicable law.