
Marine Insurance for Crude Oil Cargo
How to present crude oil shipments, distinguish quantity differences from physical loss and document valuation, quality and transit boundaries.
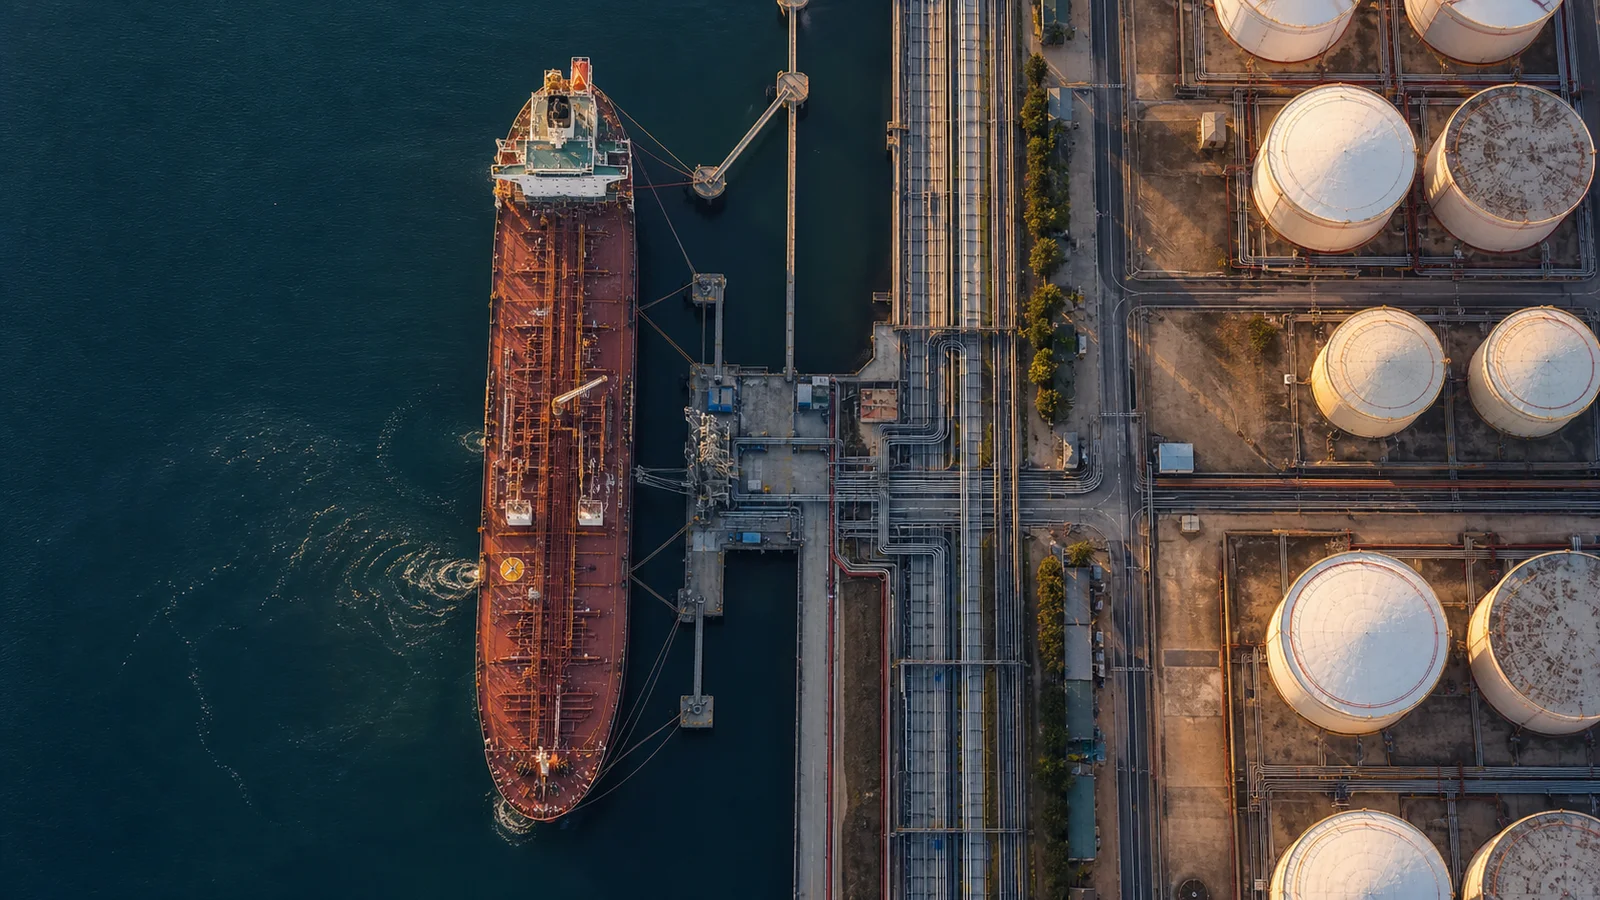
AI-generated editorial illustration.
> Editorial draft — pending specialist insurance and, where relevant, legal/compliance review. Updated 7 September 2026. Examples are hypothetical; the issued policy and applicable law determine actual cover.
Crude oil cargo insurance protects the agreed interest in a bulk commodity whose quantity, quality and value require careful documentation. A difference between loading and discharge figures can be commercially significant, but it does not by itself explain what happened or establish an insured loss.
The strongest cargo submission combines the commercial transaction with the physical movement. It identifies the insured party, valuation, vessel, route, custody changes and measurement evidence that will support a claim if something goes wrong.
Identify the sale and insured interest
Review the sale contract, delivery term and any chain of sales during transit. Establish when risk transfers and which party has the financial exposure at each stage. The party paying freight or arranging insurance is not necessarily the party bearing risk throughout the journey.
The ICC’s Incoterms rules provide a primary reference for the insurance obligations associated with CIF and CIP, but the full sale contract still matters. Parties may agree additional terms, and other delivery rules allocate responsibilities differently. See ICC: Incoterms 2020 insurance responsibilities.
Name the insured and any bank or loss-payee interests accurately. If documents will be endorsed or the cargo sold afloat, agree the intended process with the insurer. Avoid leaving claims entitlement to be resolved only after a casualty.
Define the cargo and valuation
Provide the grade, origin, quantity, currency and agreed valuation basis. Identify whether the invoice includes freight or other charges before adding them again. If the value is provisional because pricing is determined later, explain the mechanism and ask how declarations should be updated.
Check the highest exposure per vessel, transfer and storage location. Several parcels or interests can accumulate during the same operation. Annual turnover is useful for programme planning but does not replace a maximum single-loss assessment.
Distinguish physical loss protection from commodity-price risk. A fall in market value, an unfavourable pricing formula or a buyer’s inability to pay requires separate commercial analysis. Cargo insurance should not be described as protecting every financial consequence of an oil trade.
Make the transit boundaries explicit
Describe the point at which insured transit begins and ends, including relevant shore lines, tanks, loading, sea carriage, transfers and discharge. A tanker voyage can involve custody changes that are not obvious from port names alone.
If ship-to-ship transfer, floating storage or extended terminal storage is planned, disclose the operation, duration and parties responsible. Ask whether the proposed wording includes it and whether surveys or prior notices are required. Do not rely on a general warehouse-to-warehouse phrase for a bulk oil chain without examining the actual clause.
Provide a realistic itinerary and report changes through the agreed process. A diverted vessel or revised discharge plan may affect underwriting, compliance and the location of the insured interest.
Understand quantity differences
Bulk liquid measurements can differ because of measurement methods, temperature corrections, calibration, water or sediment, and material remaining aboard. Ullage is the distance from a reference point to the liquid surface; it is part of a measurement process rather than an insurance conclusion.
A shortage allegation therefore needs a consistent comparison of loading and discharge evidence. Skuld’s loss-prevention guide discusses discrepancies between shore figures and vessel measurements as a source of liquid-cargo claims. See Skuld: Safely with Skuld loss-prevention guide.
Preserve survey reports, tank tables, temperatures, samples, transfer records and any protests about discrepancies. The practical objective is to distinguish a documented physical loss from measurement uncertainty or a contractual tolerance issue. Qualified surveyors should perform the technical analysis.
Address quality and contamination
Cargo quality can be affected at different points in the supply chain. Provide the relevant specification, sampling procedure and chain of custody. Retained samples should be identifiable by location, time and person responsible so later testing can answer a meaningful question.
Review contamination and shortage provisions in the proposed policy, including deductibles and exclusions. A rejected cargo is not automatically a total loss. Depending on the facts, mitigation may involve testing, segregation, treatment or an alternative use, subject to technical and insurer guidance.
The vessel operator’s liability and the cargo owner’s property claim remain separate. Both teams may need the same samples and records, so coordinated evidence preservation is valuable even where responsibility is disputed.
A hypothetical discharge discrepancy
A buyer compares a shore loading figure with a discharge terminal figure and identifies a shortfall. The vessel’s records show a different loaded quantity and a small amount remaining aboard. The cargo insurer requests the underlying measurement data rather than accepting the first subtraction as the loss amount.
The survey review aligns units, reference temperatures, calibration and the treatment of water. It also examines whether cargo physically escaped, remained in the system or was differently measured. The outcome may support a claim, reduce the alleged amount or reveal a non-insured commercial issue.
This hypothetical shows why the evidence pack should be designed before loading. Once tanks and lines have been reused, missing measurements or samples can be difficult to recreate.
Include compliance in the transaction file
Record cargo origin, vessel and ownership details, counterparties, ports and payment arrangements. Sanctions-sensitive facts require current specialist review; an insurance quote is not legal permission to trade. OFSI’s maritime guidance is a relevant UK starting source. See OFSI financial sanctions guidance for maritime shipping.
Before attachment, confirm the final value, wording, route, insured interests and any survey conditions. Give the receiving team clear instructions for preserving evidence and notifying a suspected loss promptly.
Frequently asked questions
Does a discharge shortage automatically prove a claim?
No. Measurement bases, physical loss, contract terms and the insurance wording must be examined. Consistent survey evidence is essential.
Can crude oil stored temporarily be insured?
Possibly, if the storage and duration are declared and accepted. Transit cover should not be assumed to include indefinite storage or every transfer operation.
Does cargo insurance cover pollution liability?
Property insurance for the oil and legal liability for pollution are different interests. Discuss both and identify the relevant policy for each.
Related reading and next step
Marine Cargo Insurance: Coverage, Cost and Application Guide; How Energy Cargo Insurance Protects High-Value Shipments; Marine Pollution Liability Insurance Explained.
Prepare a marine insurance enquiry with the relevant vessel, cargo and voyage details. Availability requires underwriting, compliance review and confirmed capacity. An enquiry, estimate or payment does not by itself establish cover.
Sources and editorial review
- Skuld: Safely with Skuld loss-prevention guide
- ICC: Incoterms 2020 insurance responsibilities
- OFSI financial sanctions guidance for maritime shipping
Prepared by the MarineEnergyCover editorial desk. No individual expert reviewer has yet approved this draft. Source references describe their own legal regimes or policy forms and do not establish MarineEnergyCover’s regulatory status, authority or available terms.
Frequently asked questions
Does a discharge shortage automatically prove a claim?
No. Measurement bases, physical loss, contract terms and the insurance wording must be examined. Consistent survey evidence is essential.
Can crude oil stored temporarily be insured?
Possibly, if the storage and duration are declared and accepted. Transit cover should not be assumed to include indefinite storage or every transfer operation.
Does cargo insurance cover pollution liability?
Property insurance for the oil and legal liability for pollution are different interests. Discuss both and identify the relevant policy for each.
Sources & further reading
- Skuld: Safely with Skuld loss-prevention guide
- ICC: Incoterms 2020 insurance responsibilities
- OFSI financial sanctions guidance for maritime shipping
General information, not a coverage determination or offer. Actual cover is subject to policy wording, insurer terms, underwriting and applicable law.