
Shipyard Insurance: Separate Yard Assets and Customer Vessels
Organise shipyard insurance around owned property, construction interests, customer vessels, legal liabilities, employees and interruption exposures.
AI-generated editorial illustration.
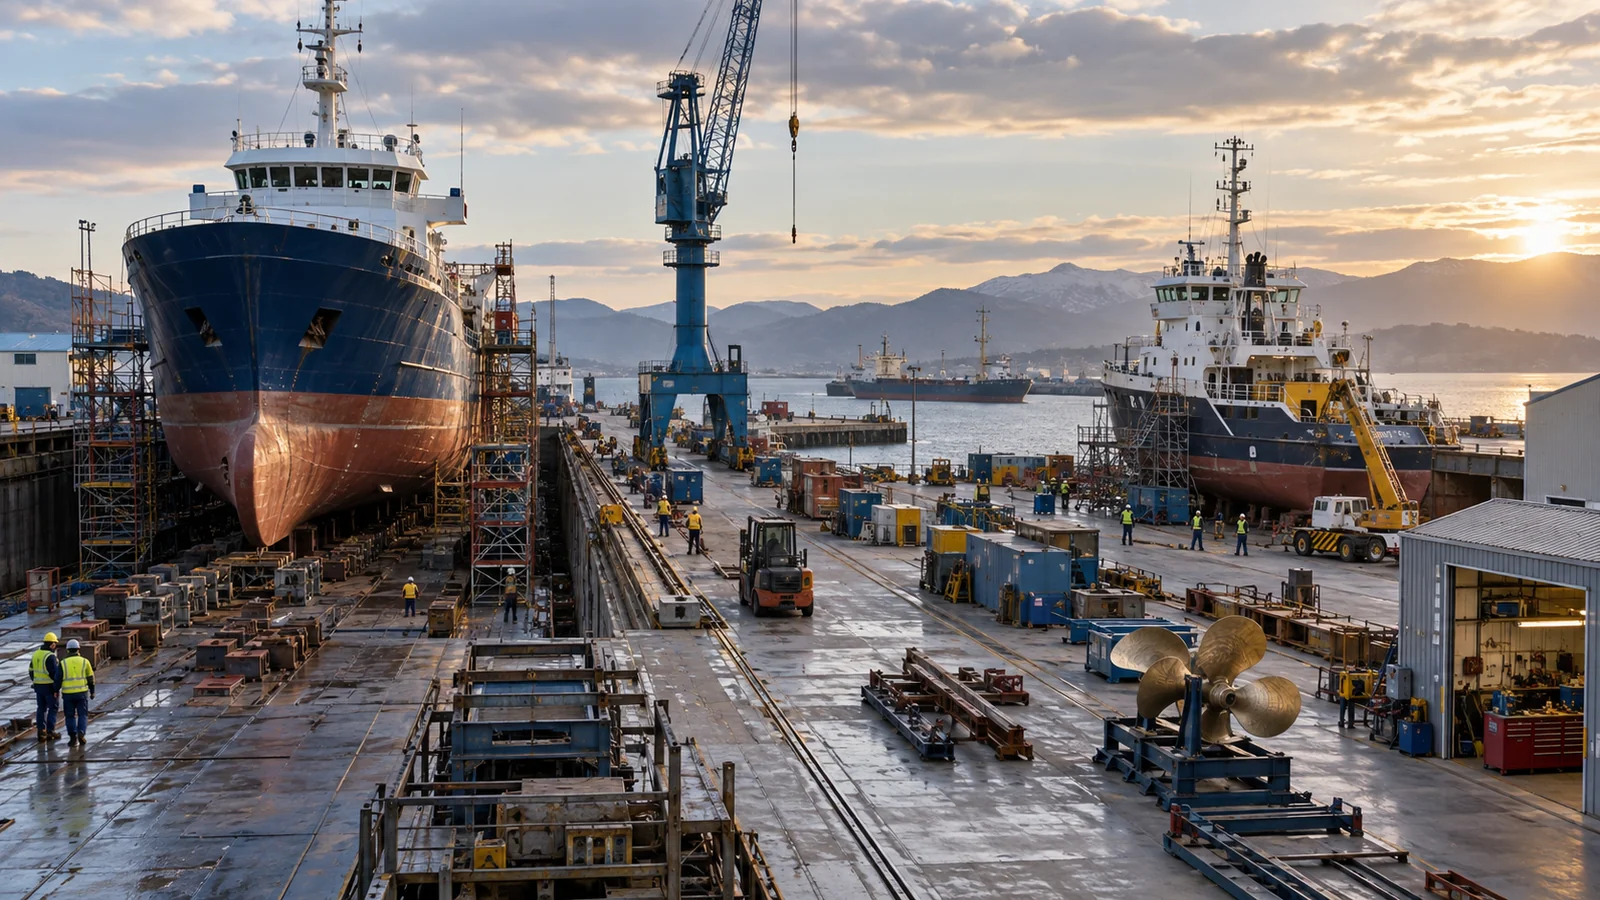
One shipyard can contain buildings, cranes, vessels under construction, customer vessels and contractors' equipment. Insuring only the yard's property leaves unanswered questions about customer interests and liabilities.
How should shipyard insurance be organised?
Organise shipyard insurance around owned property, construction interests, customer vessels, legal liabilities, employees and interruption exposures. Each needs a defined insured interest and appropriate terms. A single package may coordinate sections, but its name does not establish that every asset, activity or contractual obligation is covered.
Use a yard exposure map
| Area of the yard | Interest to identify | Potential insurance discussion |
|---|---|---|
| Workshops and cranes | Yard-owned assets | Property and equipment |
| New-build berth | Construction project interests | Builders risk |
| Repair dock | Customer vessels and yard responsibility | Owner's property cover and repairers liability |
| Design office | Professional services | Professional liability where relevant |
| Shared access areas | Employees, contractors and visitors | Applicable employer and third-party liabilities |
Marsh's shipyard guidance describes several distinct classes relevant to yards. This exposure map is a purchasing aid, not a statement that MarineEnergyCover offers every class or that one insurer will accept the whole risk.
A fictional shared-crane incident
A yard crane damages both a new-build component and a customer's vessel. The incident crosses owned equipment, project property and legal liability interests. The policies' definitions, exclusions, deductibles and recovery arrangements need to be reviewed separately.
Keep an incident chronology and identify ownership of every affected item. Do not assume that all property inside the fence belongs to the yard or falls under its property sum insured.
Present values and activities clearly
For underwriting, provide a site plan, construction and protection details, major equipment, maximum vessel values, project schedules, subcontractors, turnover by activity and loss history. Identify natural-hazard exposure, hot work, lifting, dry-docking and vessel movements.
Show peak accumulations. A yard with several valuable vessels alongside may have a different loss concentration from its average monthly activity. Explain whether adjacent businesses share utilities, cranes or emergency access.
Review the uncomfortable interfaces
Ask about faulty workmanship, design, pollution, contractual indemnities, testing, trials and business interruption triggers. A project delay or loss of future work is not automatically covered by physical damage insurance. Confirm how the programme treats damage to customer property in custody.
Contracts with owners and subcontractors should be reviewed alongside the proposed insurance. Terms requiring additional insured status, waivers or unusual indemnities need explicit assessment rather than a certificate issued without checking the underlying obligation.
Keep claims evidence by interest
Following a loss, preserve work orders, ownership records, equipment data and safety documentation. Notify potentially relevant insurers and coordinate surveys. Separate repair costs, liability demands and interruption calculations so each can be assessed on its own basis.
Read marine insurance fundamentals and hull cover. Explore the insurance categories and discuss the yard's operations before requesting a coordinated specialist proposal.
Key takeaways
- Organise shipyard insurance around owned property, construction interests, customer vessels, legal liabilities, employees and interruption exposures.
- No. Review repair contracts, liability allocation, waivers and each policy rather than assuming the owner's cover protects the yard.
Frequently asked questions
How should shipyard insurance be organised?
Organise shipyard insurance around owned property, construction interests, customer vessels, legal liabilities, employees and interruption exposures. Each needs a defined insured interest and appropriate terms. A single package may coordinate sections, but its name does not establish that every asset, activity or contractual obligation is covered.
Can a yard assume the vessel owner's insurance covers its negligence?
No. Review repair contracts, liability allocation, waivers and each policy rather than assuming the owner's cover protects the yard.
Sources & further reading
General information, not a coverage determination or offer. Actual cover is subject to policy wording, insurer terms, underwriting and applicable law.